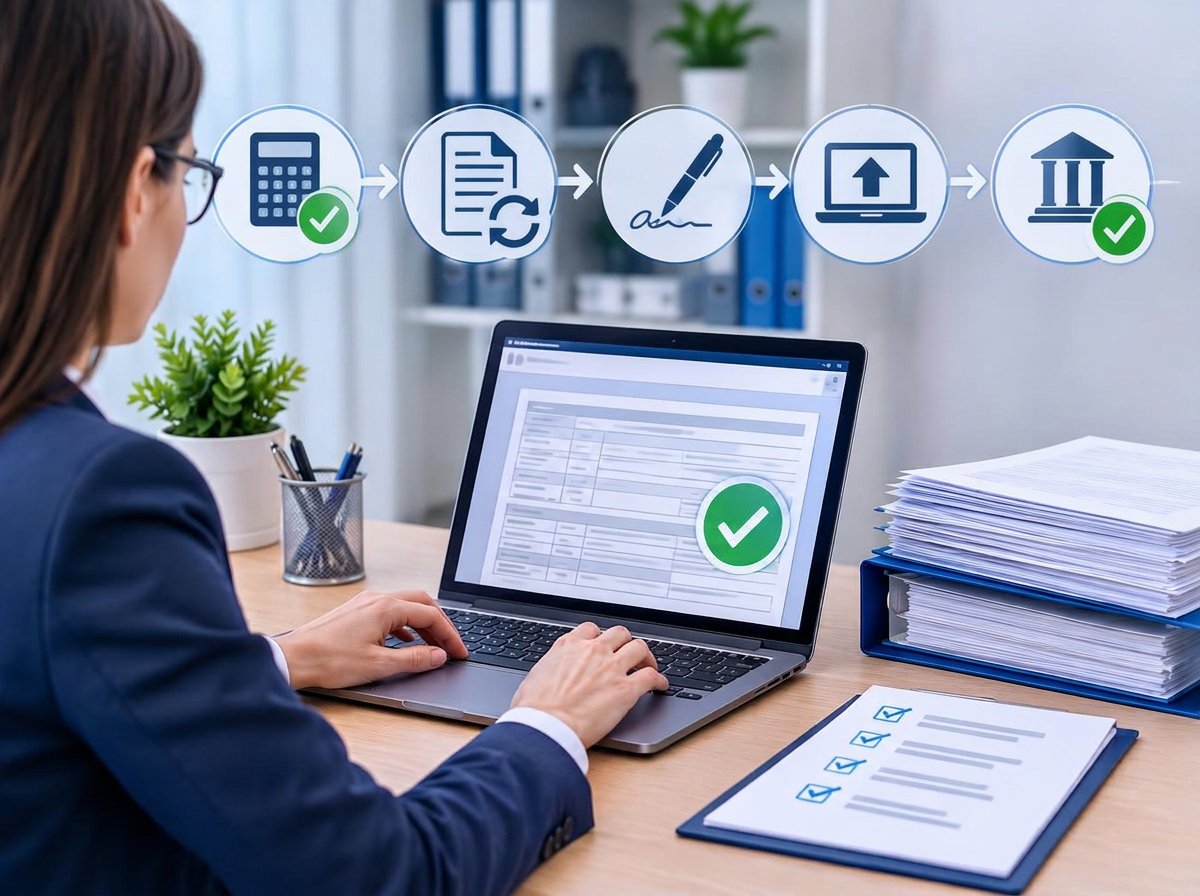
The Romanian compliance with payroll taxes does not finish when the salary calculation is approved. The employer (or the taxpayer, depending on the situation) must also convert the final payroll data into the correct version of the Form 112, arrange for an authorized person to sign and submit the salary tax form through the available electronic channel, and confirm that the tax authority has validated it.
Therefore, a payroll file that was calculated correctly but signed by a person without filing rights, submitted under the wrong taxpayer code or left with validation errors can still result in a missed or defective filing.
In this article we explain how one should submit the salary tax form correctly. It focuses on who may sign and submit the salary tax form (Form 112) and how the relevant electronic filing right must be registered. It explains what an outsourced payroll provider should receive from the employer, and which evidence should be retained after submission. It does not replace the technical instructions for completing every field in Form 112, and it does not determine whether a particular employee or foreign employer must be included in the Romanian payroll.
The short answer on who can sign and submit the salary tax form
Form 112 must be filed electronically by or for the taxpayer that has a Romanian salary tax and social contributions reporting obligation. To submit the salary tax form, the filer must use a qualified electronic signature. The electronic signature certificate holder may be the taxpayer, the legal representative, or any authorized representative, including an appropriate person at an external payroll or accounting provider. This involves that the qualified digital certificate and filing right have been registered with the tax authorities (ANAF) for the relevant taxpayer’s identification code.
The employer remains legally responsible towards the authorities for its reporting obligation even when preparation and submission are outsourced. Before a provider can submit the salary tax form, the employer should confirm that the signer has a valid qualified certificate, is registered for the correct taxpayer and tax identification number, uses the correct reporting-period version of the Form 112, and returns evidence that the declaration was accepted and validated by the authorities.
What Form 112 covers
Form 112 is the Romanian regular monthly declaration which all employers and other types of taxpayers use for reporting salary income tax and social contributions, as well as the nominal insured-persons record. All relevant employers, employer-equivalent entities and other specified payers must submit it electronically. For ordinary monthly employer filings, the deadline to submit the salary tax form is generally the 25th day of the month following the reporting month. Certain eligible taxpayers may do quarterly filing, but this depends on the type of taxpayer and whether they may opt to file quarterly instead of monthly.
You must ensure that you always use the version of Form 112 which applies to the specific month you are reporting. For example, ANAF introduced an updated version starting with July 2026, along with new preparation software, validation rules and an XSD schema. A form accepted for an earlier month may no longer be valid for a later reporting period, so the applicable version should be checked before each submission.
The taxpayer and the signer have different roles
The reporting obligation belongs to the employer or other person identified as per the Romanian tax rules. The electronic signer is the person whose qualified certificate is used to authenticate the declaration. These roles may be held by different persons: an employer may authorize a service provider’s employee to submit the salary tax form without transferring the underlying tax obligation to the service provider.
How the electronic filing right is established
Use a qualified digital certificate
Romanian tax declarations submitted remotely through electronic means (online) must be signed using a qualified digital certificate under the current Romanian electronic-signature framework and the EU eIDAS rules. A scanned handwritten signature, an electronic Adobe signature, an ordinary email signature or access to a payroll application is not a substitute for the qualified signature required for filing.
Register the certificate through Form 150
According to the procedure approved by ANAF Order 2213/2025, a qualified digital certificate and its holder must be registered for the online declaration-submission service through Form 150. The request must be completed using the online functionality and must be transmitted electronically to the competent tax authority. It must be signed by the individual taxpayer, the legal representative or designated representative, or by an authorized person, as applicable.
Generally, the person making the request who is acting under authorization from the taxpayer must prove the representative capacity. For this purpose, the electronic form must be accompanied by the relevant supporting document (generally, a special power of attorney). Some online guidance may still refer to outdated paper-based steps or previous electronic-signature rules. Employers should therefore make sure to follow the latest ANAF procedure and confirm that any instructions they use are still current.
Confirm approval before relying on the certificate
ANAF checks the request together with the supporting data. Approval or rejection is automatically communicated to the email address included in the request. Careful payroll planning should allow enough time for the registration to be approved by the authority, before the first filing deadline. Merely holding a certificate does not prove that its holder has filing rights for a specific taxpayer.
A practical onboarding workflow for an external payroll provider
The cleanest implementation workflow should separate legal authorization, technical access, payroll preparation and employer approval. The following example shows the main aspects that must be observed for a new payroll provider or a new Romanian entity.
- Confirm the exact Romanian taxpayer identification code and the entity that bears the filing obligation
- Name an employer-side payroll owner and a backup approver
- Decide whether the provider will prepare only, or will also sign and submit the salary tax form
- Identify the individual digital certificate holder
- Complete the Form 150 for registration and attach the current authorization or representation evidence (i.e., power of attorney)
- Verify approval is confirmed for the correct taxpayer before the live filing month
- Test the end-to-end process using the correct D112 software and validation package for the reporting period
- Agree the payroll cut-off, approval deadline, filing deadline, payment deadline and escalation path
- Define which evidence the payroll provider must return after submission and how quickly it must escalate any errors
What should be approved before form submission
Before the authorized person can submit the salary tax form, it would be advisable for the employer to have in place an agreed approval pack with the provider. This should connect the detailed employee data to the declared totals and cover some control keys such as:
- the reporting month and the Form 112 version applicable to that month
- the taxpayer identification data and any late changes
- employee population, starters, leavers, suspensions and identifier changes
- gross salary, taxable and non-taxable benefits, special exemptions, deductions and contribution bases
- salary income tax, CAS, CASS and employer contribution totals
- medical leave and insured-person data, where relevant
- comparison with payroll registers, payment files and the general ledger
- explanations for material month-on-month movements
- the person authorized to release the declaration for signature and submission
Submission is not complete until status is checked
Successful upload of the tax form on ANAF’s platform is only one stage of the process. ANAF guidance instructs filers to check the status of Form 112 after submission. If the status receipt reports errors, the form should be corrected and resubmitted within the legal filing deadline. The internal file should therefore contain both the transmission evidence and the final validation evidence.
A useful operating standard is to require the provider to return the signed declaration, submission receipt, status result, and a summary that reconciles the accepted filing to the employer-approved totals. The employer should not accept “submitted” as a sufficient status where the provider cannot show whether the form was validated by the authorities.
What happens if the form submission receipt contains an error
The current Form 112 instructions allow taxpayers to correct the form on their own initiative by filing a rectifying return. A rectifying return may correct salary tax and contribution amounts, employee identification data, insured periods, medical-leave information, omitted persons and other reported information. The rectification must be completed on the same form model and, as a general rule, contains the full declaration data rather than only the changed line.
The correction process should distinguish three situations. A technical rejection and non-validation of the form normally requires it to be corrected and resubmitted. An accepted and validated form containing incorrect payroll data would require submitting a rectifying one. A change to the underlying payroll may also require accounting, payslip, payment and employee-record corrections. The employer should assess the complete chain rather than treating the declaration as an isolated XML or PDF problem.
Changing the signer or payroll provider
If the certificate holder leaves the company, changes roles or stops providing payroll services, check whether they still need to file tax returns on the company’s behalf. As soon as they no longer need access, request its removal using Form 151, as provided by ANAF Order 2213/2025.
You can also submit the Form 151 online. If you sign it by hand, you can submit the paper form at an ANAF tax office. ANAF will send confirmation of the signing right revocation to the email address you provide on the form.
A provider transition should therefore include both sides of access management: the incoming signer must receive approved access early enough to test and submit the salary tax form, and the outgoing signer’s rights must be revoked when no longer needed. Therefore, it would be useful for the employer to retain an access register tracking all the details such as: the certificate holder, taxpayer codes, approval date, certificate expiry, backup arrangements and revocation date.